Insights
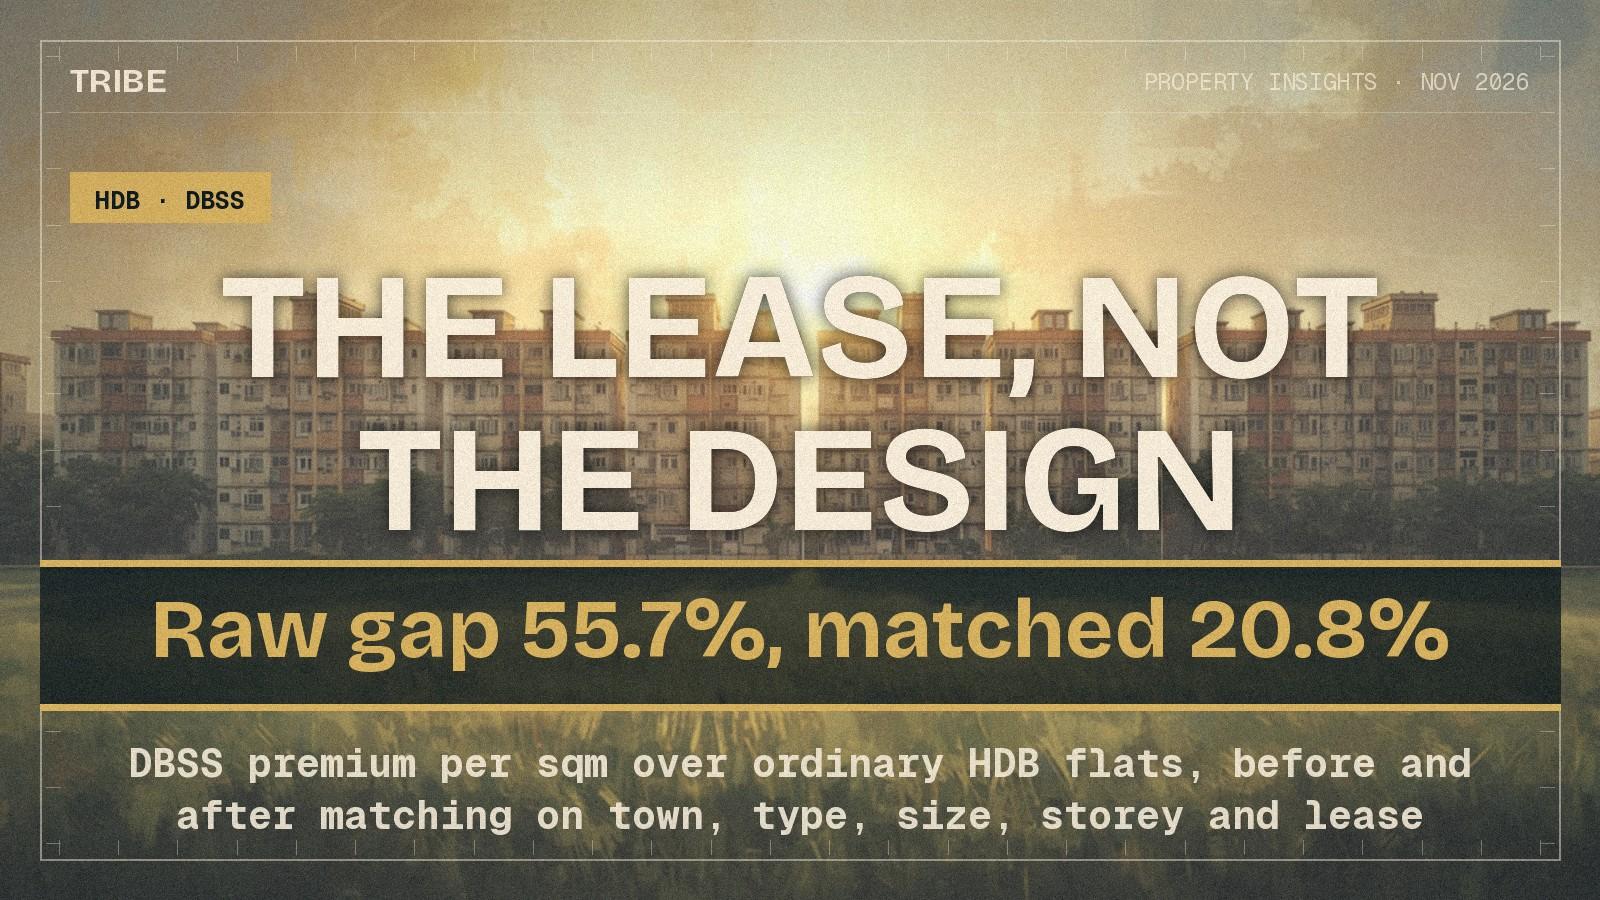
A DBSS Flat Costs 56% More Per Square Metre. Matched on Age, 21%.
DBSS flats sell for 55.7% more per square metre than ordinary HDB flats. Match them on town, flat type, size, storey and remaining lease and the gap is 20.8%. Most of the rest is 17.6 years of extra lease.
By TRIBE Research · 14 November 2026 · 8 min read
The decision
- Who this is for
- HDB buyers comparing a DBSS flat with an ordinary flat of similar age in the same town, and DBSS owners weighing a sale.
- The question
- Is the DBSS price difference the flat itself, or just a newer lease?
- The short answer
- Mostly the lease. Compare flats in the same town, flat type, size band, storey band and remaining-lease band and the DBSS flat sells for a median 20.8% more per square metre, not 55.7%. The matched premium has narrowed to 15.0% in 2026, and it is 29.5% in Yishun against 0.3% in Clementi.
- Next step
- Check what flats of the same age and size actually sold for in that town before accepting a DBSS asking price.
The numbers behind it
- 20.8% per square metreMedian premium over ordinary flats matched on town, type, size, storey and lease.
- 15.0% in 2026The same matched premium this year, against 34.2% in 2019-2020.
- 29.5% against 0.3%Matched premium in Yishun against the one in Clementi.
A DBSS flat sells for a median $8,260 per square metre, about $767 per square foot. An ordinary HDB resale flat sells for $5,304, about $493. That is 55.7% more, and it is the comparison most buyers are shown. Compare flats in the same town, of the same type, size and height, with the same remaining lease, and the difference is 20.8%.
The premium is real. It is also a fifth, not a half, and it has been shrinking.
The question a DBSS buyer is actually asking
Thirteen sites were built under the Design, Build and Sell Scheme, in which private developers designed, built and priced public housing. HDB stopped awarding DBSS land after the last of them. They are 1.58% of resale transactions, 3,862 of 243,867 between January 2017 and October 2026, and they carry prices that look nothing like the flats around them. In 2026, 38.3% of DBSS resales crossed a million dollars, against 7.5% of ordinary resales.
So a buyer standing in front of a DBSS flat has one question. Am I paying for the flat, or for something I could get cheaper elsewhere in this town?
The answer in plain language
Mostly the second. The median DBSS flat has 90.9 years of lease left. The median ordinary resale flat has 73.3. That is 17.6 years of difference, and lease is the single biggest thing separating the two prices.
Once you take it out, along with town, flat type, size, storey and the month of sale, a DBSS flat still costs a median 20.8% more per square metre. That is what the design, the developer finishes and the address are worth in resale. It is not nothing. It is not 55.7% either.
The strongest numbers: $8,260 against $5,304
The two groups are the same size and almost the same height. The median DBSS flat is 94 square metres; the median ordinary flat is 93. The median DBSS sale is on the 11th storey, the median ordinary sale on the 8th.
| DBSS | Ordinary HDB | |
|---|---|---|
| Median price per square metre | $8,260 | $5,304 |
| Median price | $785,000 | $500,000 |
| Median remaining lease | 90.9 years | 73.3 years |
| Median storey | 11 | 8 |
| Median floor area | 94 sqm | 93 sqm |
| Resales, Jan 2017 to Oct 2026 | 3,862 | 240,005 |
Size is not the story. Lease is.
Why the raw comparison misleads
Lease decay can be measured in the same dataset, without reference to DBSS at all. Among ordinary four-room resales of the last three years, those with 85 or more years of lease remaining sold at a median $7,241 per square metre. Those with 65 to 75 years sold at $5,714. That is 26.7% between two groups of ordinary flats, on lease alone.
Height does far less than people assume. Comparing ordinary four-room flats matched on town, size band, lease band and year, a sale on storeys 10 to 12 fetched a median 1.5% more per square metre than one on storeys 7 to 9, across 772 matched groups. The DBSS flat being three storeys higher explains almost none of the gap.
The controlled comparison, and where the premium sits
Flats were grouped by town, flat type, 10-square-metre size band, 10-year remaining-lease band, six-storey band and half-year of sale. Groups holding at least one DBSS sale and at least three ordinary sales were kept. That left 374 groups, matching 910 DBSS resales against 5,092 ordinary ones, 23.6% of all DBSS sales in the period.
The median premium across those groups is 20.8% per square metre. In 371 of the 374 groups the DBSS flat was dearer, and the three exceptions were within 6.1%. The middle half of groups ran from 13.4% to 29.4%. Narrowing the bands to five square metres and three storeys moves the figure to 22.8%; widening them moves it to 18.3%. The finding does not depend on the band widths.
Two things vary a great deal more than the band widths do. The first is time.
| Period | Matched groups | DBSS resales | Median premium |
|---|---|---|---|
| 2019 and 2020 | 94 | 291 | 34.2% |
| 2021 to 2025 | 230 | 524 | 19.1% |
| 2026, Jan to Oct | 43 | 81 | 15.0% |
The second is geography, and it runs opposite to intuition. The scheme built mostly in mature estates, yet that is where the premium has gone.
| Town | Matched groups | DBSS resales | Median premium |
|---|---|---|---|
| Yishun | 99 | 324 | 29.5% |
| Jurong West | 49 | 79 | 23.1% |
| Tampines | 49 | 121 | 20.8% |
| Hougang | 90 | 227 | 18.2% |
| Kallang/Whampoa | 18 | 28 | 12.5% |
| Ang Mo Kio | 22 | 36 | 12.0% |
| Bedok | 14 | 34 | 11.5% |
| Toa Payoh | 21 | 40 | 7.1% |
| Clementi | 5 | 9 | 0.3% |
A DBSS flat in Yishun is the best address of its vintage for some distance. A DBSS flat in Clementi is sitting beside ordinary flats of the same age that are already well located, well served and in demand, and it commands almost nothing extra for its design. The premium is not a reward for being a DBSS flat. It is what the surrounding stock of the same age fails to offer.
In cash, across matched groups since January 2025, the median gap between a DBSS flat and its comparison flats is $102,472.
What this analysis does not prove
It does not prove that paying the premium is right or wrong. These are transacted prices, not value.
Matching controls town, flat type, size, storey band, remaining lease and timing. It does not control what is inside the flat or exactly where it stands. Renovation, condition, orientation, the walk to the station and the view are all unmeasured here, and some of them are part of what a DBSS buyer is paying for. So the 20.8% is not an unexplained premium. It is the premium that survives the controls we have.
Thirteen sites is thirteen sites. Two towns in the table rest on fewer than 20 matched groups, Clementi on five, and those rows should be read as indicative. Bishan has no row at all, because no ordinary flat in Bishan has a lease close to Natura Loft's, so there is nothing to compare it with. Only 23.6% of DBSS sales found a match, so the matched set is not the whole scheme.
The narrowing from 34.2% to 15.0% is a correlation across the period, not a law. Part of it is almost certainly that DBSS flats were newly out of their minimum occupation period in 2019 and are now ordinary second-hand flats. Figures are transacted resale prices before agent fees, stamp duty, legal fees and renovation, and they exclude maintenance and conservancy charges, which differ by town council.
What this means if you are buying or selling a DBSS flat
If you are buying, the number to beat is not the DBSS median. It is what a flat of the same age, size and height in that town costs. In Yishun or Jurong West, expect to be asked roughly a fifth to a quarter more and decide whether the finishes and the address are worth it. In Toa Payoh or Clementi, a large premium is harder to justify from the resale record, because the ordinary flats of the same vintage next door are strong.
If you are selling, the 2026 figure matters. The matched premium is 15.0%, not the 34.2% of 2019 and 2020. Pricing off a DBSS comparable from a few years ago, or off the raw 55.7% gap, is pricing off a market that has moved.
Either way, the lease does most of the work. A DBSS flat with 85 years left and an ordinary flat with 85 years left are far closer than the headline medians suggest.
Next step
Take the block, the flat type and the floor, and look up what comparable flats of the same age and size have actually sold for in that town. The gap that matters is the local one, not the island-wide one.
Based on 243,867 HDB resale transactions registered between January 2017 and October 2026, published by HDB via data.gov.sg and read on 14 November 2026; November 2026 is a partial month and is excluded. DBSS flats are identified by the dataset's own flat model field, 3,862 sales across 13 sites. The controlled comparison matches on town, flat type, 10-square-metre floor-area band, 10-year remaining-lease band, six-storey band and half-year of sale, keeping groups with at least one DBSS and three ordinary sales. Figures are transacted resale prices before agent fees, stamp duty, legal fees and renovation, and exclude maintenance and conservancy charges. General information, not advice for any particular flat or household.
Your next step
Looking at a DBSS flat, or own one and weighing a sale? Send us the block, flat type and floor. We will pull what flats of the same age and size sold for in that town, and show you the local gap rather than the island-wide one.
A consultant replies on WhatsApp. No registration, no obligation.
Prefer a personal read on your situation? Arrange a consultation →Keep reading
Next step
TRIBE Research
Written with AI assistance from TRIBE's own data and the public sources listed, then checked against them. General information, not financial advice. How we write
Sources
- Resale flat prices based on registration date, from Jan 2017 onwards · Housing and Development Board, via data.gov.sg · retrieved 14 November 2026
Data as of October 2026.
How TRIBE scores and checks its analysis
Spotted an error, or a figure that has moved since publication? Tell us and we will correct it.
General information only, not financial, investment, legal or tax advice. It does not consider your own circumstances; check your own numbers before you commit.