Insights
These Are Our Top 5 Condos in Telok Blangah & HarbourFront — and Why District 4 Ranks Last
District 4 has the lowest mean RPS of any district we rank with more than two projects. Ten of its eleven D grades sit inside one enclave. Remove Sentosa Cove and the rest of the district reads perfectly normal.
By TRIBE Editorial · 20 September 2026 · 8 min read
District 4 covers Telok Blangah, HarbourFront, Keppel Bay and Sentosa. Run all 24 resale projects we score there through the Resale Project Scorecard and the district mean comes out at 4.54 out of 10 — 1.40 points below the national mean of 5.94 across 2,357 projects, and the lowest of any district with more than two projects scored. Eleven of the 24 carry a D grade: 45.8% of the district, the highest D-grade share in Singapore among districts with ten or more projects.
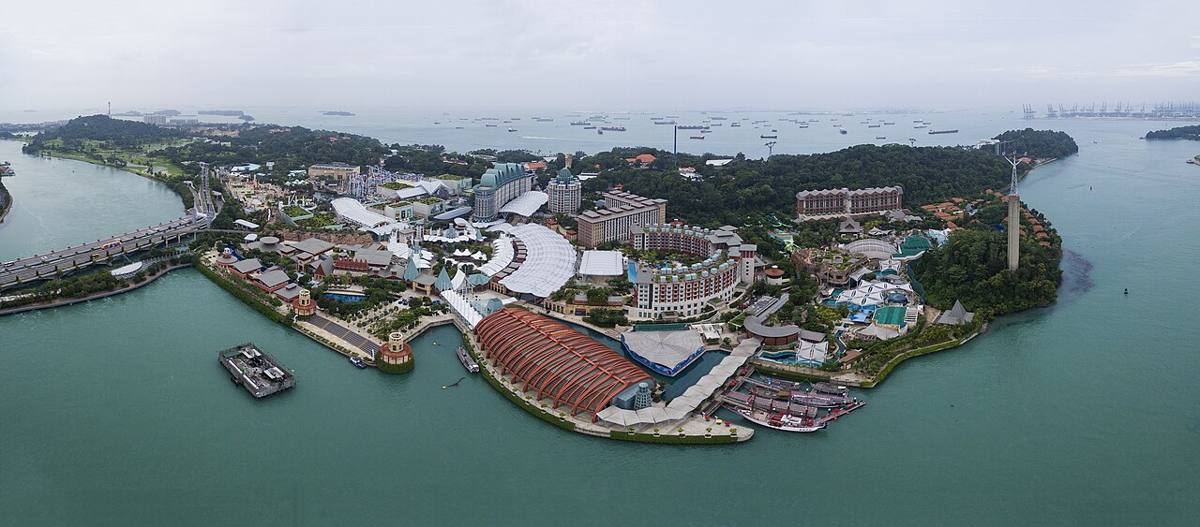
Read that as a verdict on the neighbourhood and you will misprice it. Ten of those eleven D grades sit inside Sentosa Cove. Strip the Cove out and District 4's mean rises to 5.64 — a lift of 1.09 points, or 24.0%. That is not a weak district. It is two markets sharing a postcode, and one of them is doing all the damage.
How we ranked this
The RPS grades every resale project on seven weighted factors: historical capital performance (25%), primary schools (20%), project size (16%), MRT proximity (13%), rental yield (10%), tenure (10%) and future transformation (6%). Each factor is marked out of ten and rolled into one score and a letter grade from S to D. The historical score is cohort-relative — a project is measured against others that reached TOP in the same two-year window — so age alone is not penalised, only underperformance against its own vintage.
Nothing below is an opinion about a view or a lobby. These are the district's own transaction records, scored the same way every other district is scored.
1. Teresa Ville — 6.91, grade A
The district's only A grade, and the only project here scoring a perfect 10/10 on historical performance: an average annual +3.79%, 62nd percentile of its 1986-era cohort. Freehold tenure removes the lease question entirely, and the school catchment is exceptional — Radin Mas Primary at 0.12km, three primary schools within 1km. At 264 units it is large enough for an active resale market.
The scorecard is equally blunt about the trade-off: rental yield is 2.06%, described as a weak income return, and MRT access scores 4/10 at 1.01km from Keppel (CC30) — "likely requires bus or car for most trips." This is a schools-and-tenure hold, not an income asset.
2. The Reef at King's Dock — 6.39, grade B
The newest project on the list, completed in 2024 with about 94 years of lease remaining. It scores on the two things a recent 99-year project should: tenure (8/10) and 0.49km to HarbourFront MRT (NE1 / CC29), a short walk on two lines. Rental yield is a strong 3.78%, and at 429 units the resale market is deep enough to price properly.
Its weakness is unambiguous and structural: no primary schools within 1km. For a buyer prioritising Primary 1 registration, that is not a detail to work around. Its +1.96% average annual appreciation sits at the 66th percentile of a 2024 cohort with very little history behind it — treat that score as provisional, not proven.
3. Harbour Suites @ Kampong Bahru — 6.29, grade B
Freehold, 390m from Keppel MRT (CC30) — direct walk-in access — and an exceptional catchment with CHIJ (Kellock) at 0.32km. Yield of 3.24% is above average. On paper it is the most convenient address in the top five.
The costs are real. At 44 units it is a very small project: the scorecard calls it "niche product with thin resale market," and thin liquidity means a couple of motivated sellers can set the comparable for everyone. Capital appreciation is the genuine weak spot — +0.53% a year, 33rd percentile of its 2014-era cohort, below median against its own peers.
4. The Interlace — 6.10, grade B
The scale play, and the best capital record in the top five relative to its own vintage: +2.30% a year, 75th percentile of the 2013 cohort — top quartile. At 1,040 units it has by far the deepest resale market here, with 82 years of lease remaining and a yield of 3.56%.
What it does not have is transport. 1.11km from Labrador Park (CC27) scores 4/10 — weaker access, bus or car for most trips — and school optionality is narrow, with one primary school within 1km (Blangah Rise, 0.87km). Buyers are paying for architecture, grounds and liquidity, and accepting the commute.
5. Mount Faber Lodge — 6.04, grade B
Freehold, 0.52km from HarbourFront MRT, two primary schools within 1km with Radin Mas at 0.68km. Appreciation is mid-pack for its vintage: +2.93% a year, 43rd percentile of a 1983 cohort. A dependable, unspectacular profile.
The same two caveats as Harbour Suites apply, harder. At 84 units the resale market is thin, and rental yield of 2.44% is weak. Freehold tenure near an MRT station is doing most of the work in this score.
The enclave that makes the district average
Now the other market. Ten Sentosa Cove projects score between 2.46 and 3.48, mean 3.01, every one of them a D. And they do not fail on assorted different factors — they fail identically. All ten score 1/10 on historical capital performance and 1/10 on MRT access.
| Project | RPS | Avg annual | Cohort rank |
|---|---|---|---|
| The Residences @ W Sentosa Cove | 3.48 | −0.09% | bottom 15% |
| The Oceanfront @ Sentosa Cove | 3.43 | −0.25% | bottom 14% |
| Cape Royale | 3.40 | 0.00% | bottom 13% |
| The Coast @ Sentosa Cove | 3.20 | −0.70% | bottom 7% |
| The Azure | 3.11 | +0.03% | bottom 11% |
| The Berth By The Cove | 2.95 | +0.60% | bottom 4% |
| Marina Collection | 2.79 | −3.21% | bottom 5% |
| Seven Palms Sentosa Cove | 2.67 | −1.59% | — |
| Seascape @ Sentosa Cove | 2.65 | −3.42% | bottom 4% |
| Turquoise | 2.46 | −3.88% | bottom 4% |
Seven of the ten have gone backwards. The mean is −1.25% a year and the median −0.25%. Not one project reaches +1%. Over the same span the mainland projects in this district ran between +0.53% and +3.79%. These are not soft returns; they are negative returns against cohorts that were themselves only mid-pack.
The MRT score is simply geography — the nearest rail is Sentosa Express or Prince Edward Road, 1.92km to 2.88km away, and the scorecard treats that as weak access for everyone equally. The capital record is the part that matters, and it is worth saying plainly what the RPS does and does not claim. It measures the outcome. It does not attribute a cause.
The obvious candidate for one sits in the duty schedule. Sentosa Cove is the only place in Singapore where a foreigner may buy a restricted residential property with approval, and since 27 April 2023 a foreigner has paid 60% ABSD on a residential purchase. On a S$5 million unit that is S$3,000,000 of ABSD on top of S$239,600 of BSD — S$3,239,600, or 64.8% of the price, payable at stamping. Whatever else that does, it thins the buyer pool an enclave built for exactly that buyer depends on. Check the current figures against IRAS before relying on them.
The reusable point
A district average is not a market. District 4's 4.54 is arithmetically correct and practically misleading, because it averages a waterfront enclave with almost no rail access and a negative capital record against a mainland belt that scores like any other Rest-of-Central district. Our own Woodlands review made the same point from the opposite direction: one outlier at the bottom of a 14-project town told you nothing about the other thirteen.
Before you accept any district-level number — a mean RPS, a median psf, a rental yield — ask what sub-markets it is averaging and whether a buyer could actually choose between them. Here, they cannot. Nobody shortlists a Telok Blangah freehold walk-up and a Sentosa Cove waterfront apartment as substitutes. Averaging them produces a number that describes neither.
Scores and quoted reasons are from the Resale Project Scorecard as published at the date of this article, computed from URA REALIS transaction records. Grades change as new transactions land. Methodology published. No spin.
Check how your condo scores
2,357 condos independently scored across 7 weighted factors. No registration required.
Score my resale →Prefer a personal read on your situation? Arrange a consultation →Keep reading
TRIBE Editorial · Reviewed by Silas Tan
Co-Founder, TRIBE · District Director, Huttons Asia · Ex-Mortgage Banker (AVP) · >1,000 families advised · CEA R000303I
This article is for informational purposes only and does not constitute financial or investment advice.