Insights
New Launch vs Resale Condo in 2026 — The Worked Math
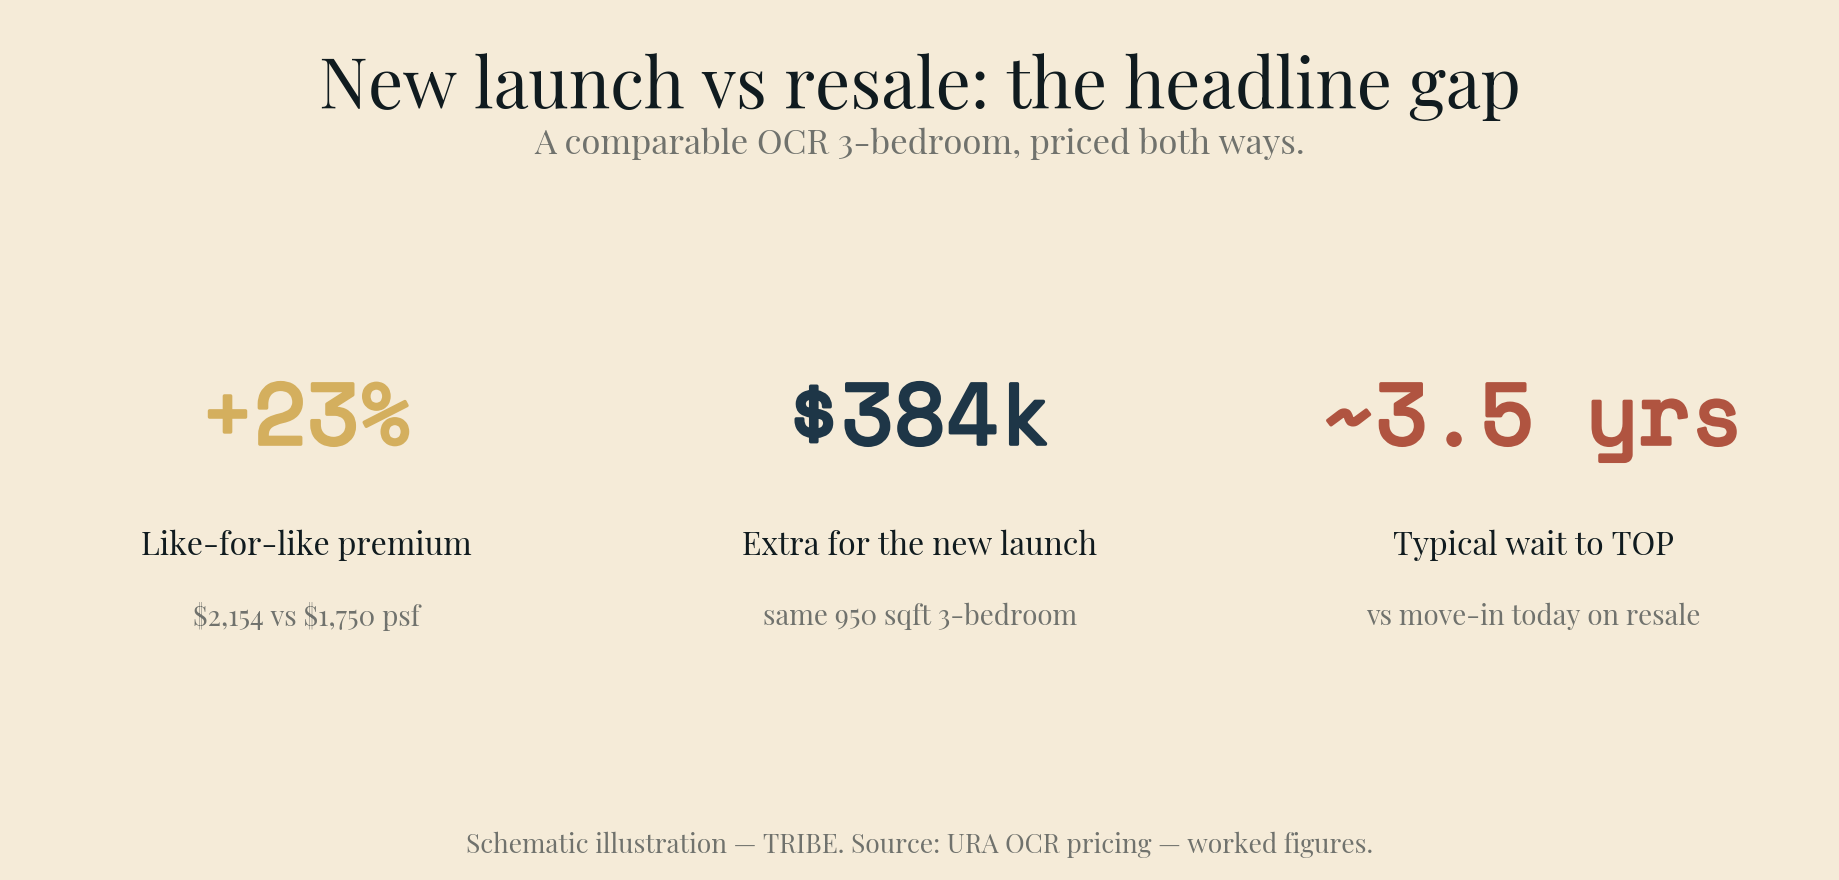
A new OCR launch runs about 23% more per square foot than a comparable resale — roughly $384,000 on the same 950 sqft. But the gap buys deferred financing and a fresh lease, while resale buys space today. We run both columns on the same flat.
By TRIBE Research · 16 June 2026 · 6 min read
The choice between a new launch and a resale condo is usually framed as new-and-expensive versus old-and-cheap, and that framing hides the actual decision. In the Outside Central Region right now, new launches average about S$2,154 per square foot against roughly S$1,545 for resale — a 39% headline gap. But that compares a brand-new project to the entire resale pool, most of which is older and smaller-lease. Put a new launch next to a comparable five-to-seven-year-old resale unit and the premium narrows to the 20–30% developers actually command. The real question isn't which is cheaper. It's what the premium buys, and whether what it buys is worth roughly S$384,000 and a multi-year wait. So we ran both columns on the same flat.
The same flat, two ways
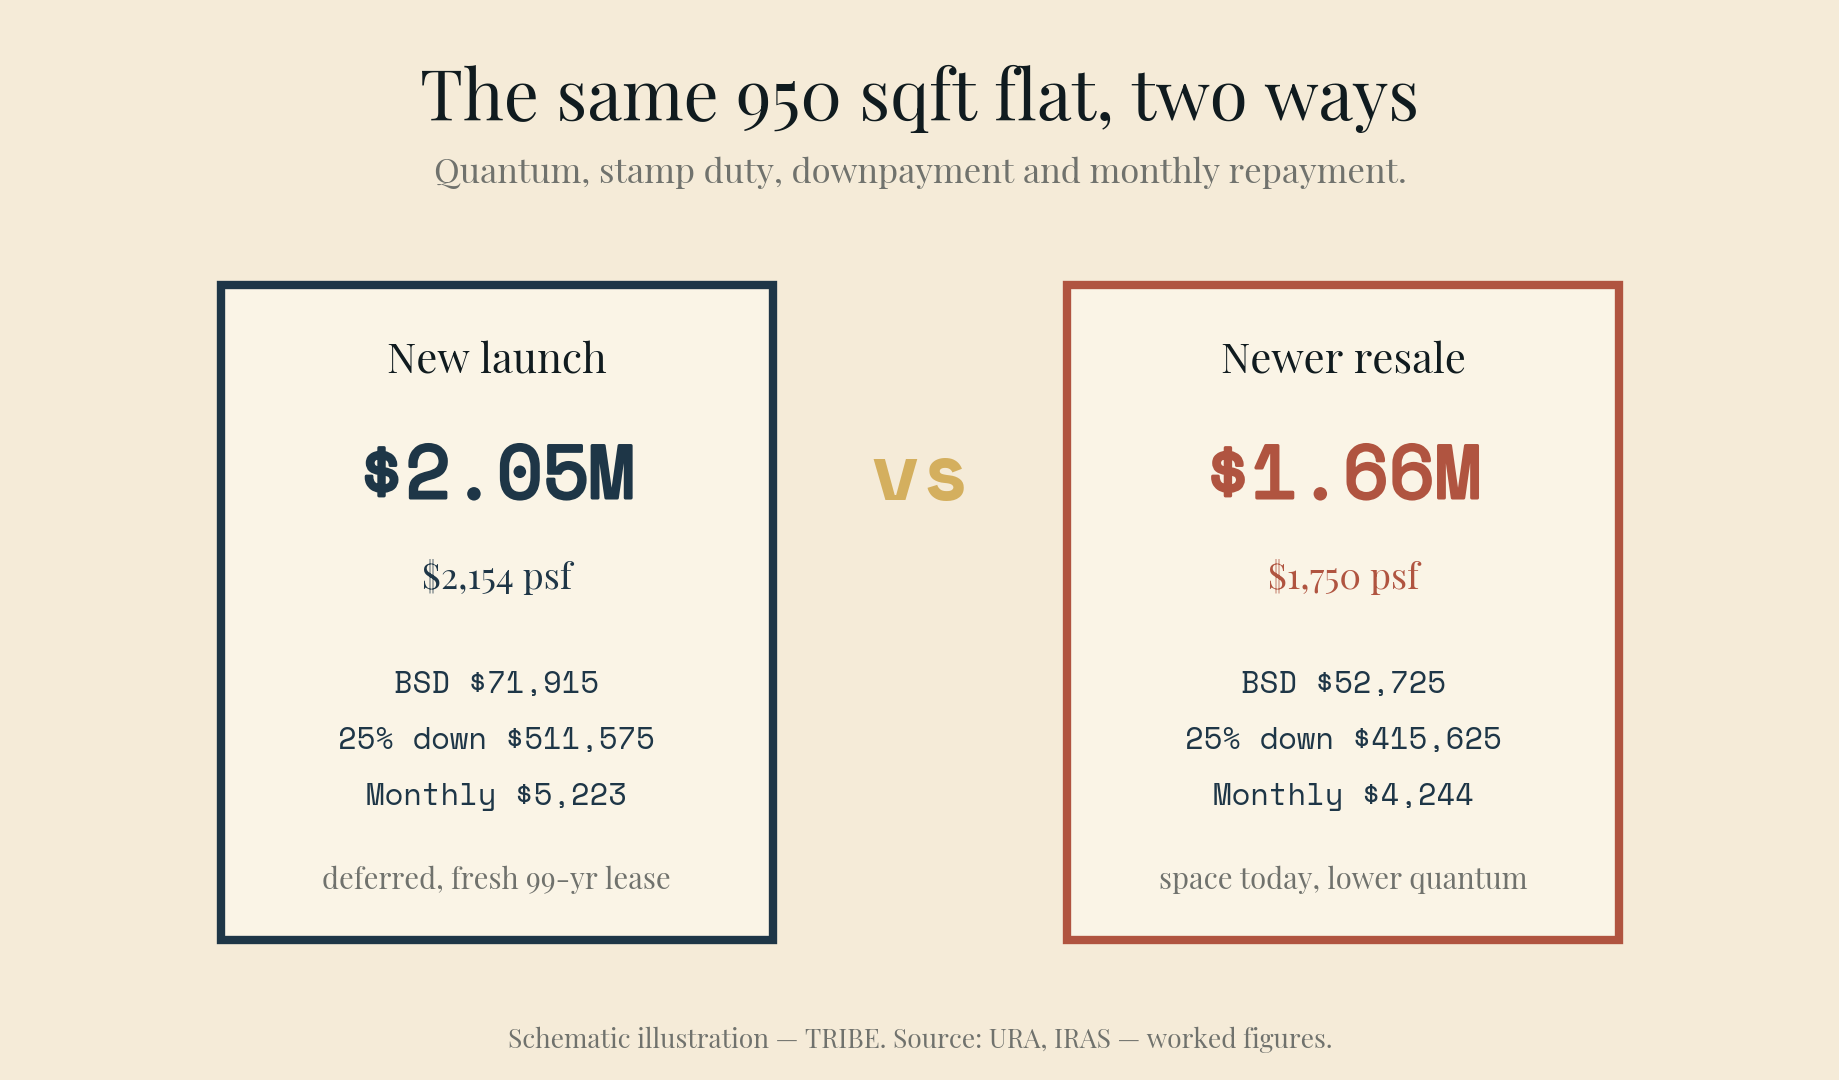
Take a 950 sqft three-bedroom in the OCR — the bread-and-butter upgrader unit. We price the new launch at the OCR new-sale average of S$2,154 psf, and a comparable newer resale at S$1,750 psf (above the resale-pool average, because we're matching age and condition, not cherry-picking the oldest stock). Financing assumes 75% loan-to-value at a 1.40% fixed rate — around mid-2026's sharpest new-purchase pricing — over 30 years. Buyer's Stamp Duty is computed at the 2026 residential tiers. These are illustrative figures with stated assumptions, not quotes.
| New launch | Newer resale | |
|---|---|---|
| Price psf | S$2,154 | S$1,750 |
| Quantum (950 sqft) | S$2,046,300 | S$1,662,500 |
| Buyer's Stamp Duty | S$71,915 | S$52,725 |
| 25% downpayment | S$511,575 | S$415,625 |
| 75% loan | S$1,534,725 | S$1,246,875 |
| Monthly (30y, 1.40%) | S$5,223 | S$4,244 |
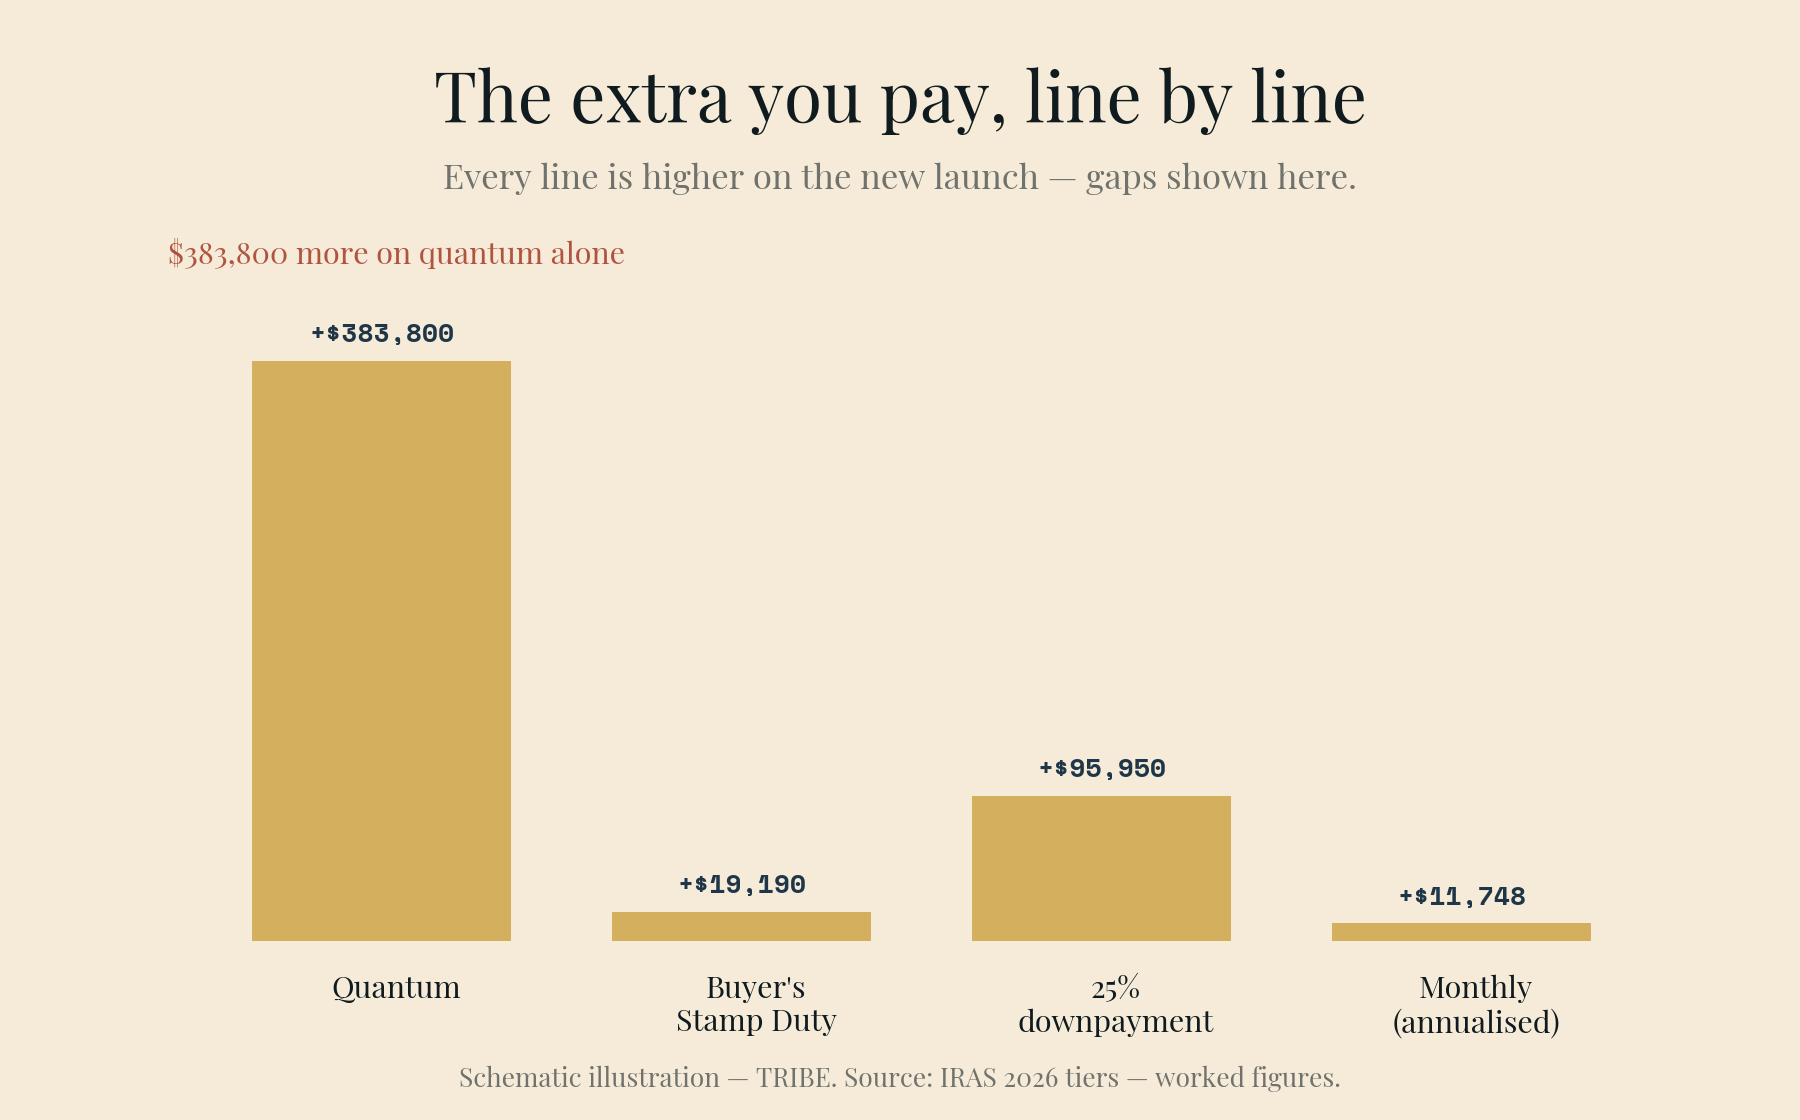
The premium is S$383,800 on the quantum — about 23%. The upfront cash-and-CPF gap (downpayment plus stamp duty) is roughly S$115,000, and the monthly repayment runs about S$980 more. None of that is hidden; it's the visible cost of buying new. What's less visible is what sits on the other side of the ledger.
What the premium buys: deferred financing and a fresh lease
A new launch is bought under the Progressive Payment Scheme, and that changes the shape of the outlay, not just the size. You pay a 5% booking fee, 15% on signing the Sale & Purchase Agreement about eight weeks later, then stage payments of 10–11% as construction hits each milestone, with the largest tranche — around 25% — due only at Vacant Possession. Critically, your bank disburses the loan in step with those stages, so you pay interest only on what's been drawn. In the first year of a new launch, with perhaps a fifth of the loan disbursed, the interest carried is a fraction of a fully-drawn loan's. The resale buyer, by contrast, draws the entire S$1.25M loan on completion and pays interest on all of it from month one.
The new launch also resets the lease to a full 99 years and hands over a unit with no immediate renovation bill — against a resale flat that starts its lease clock years earlier and typically needs S$30,000–S$80,000 of work before move-in. For a buyer planning to hold a decade or more, a fresh lease and developer-grade fittings are real value the per-square-foot premium is partly paying for.
What the premium costs: three-plus years without the space
Here is the other side, and it's the one new-launch marketing tends to mute. The resale buyer occupies — or rents out — the unit immediately. The new-launch buyer waits roughly three and a half years to TOP, during which the property produces nothing. On a S$1.66M unit at a ~3.4% gross yield, that's about S$50,000 a year of occupation value or rental income forgone — on the order of S$175,000 across the wait. And the new-launch buyer is usually still paying for somewhere to live in the meantime, whether that's rent or an existing mortgage.
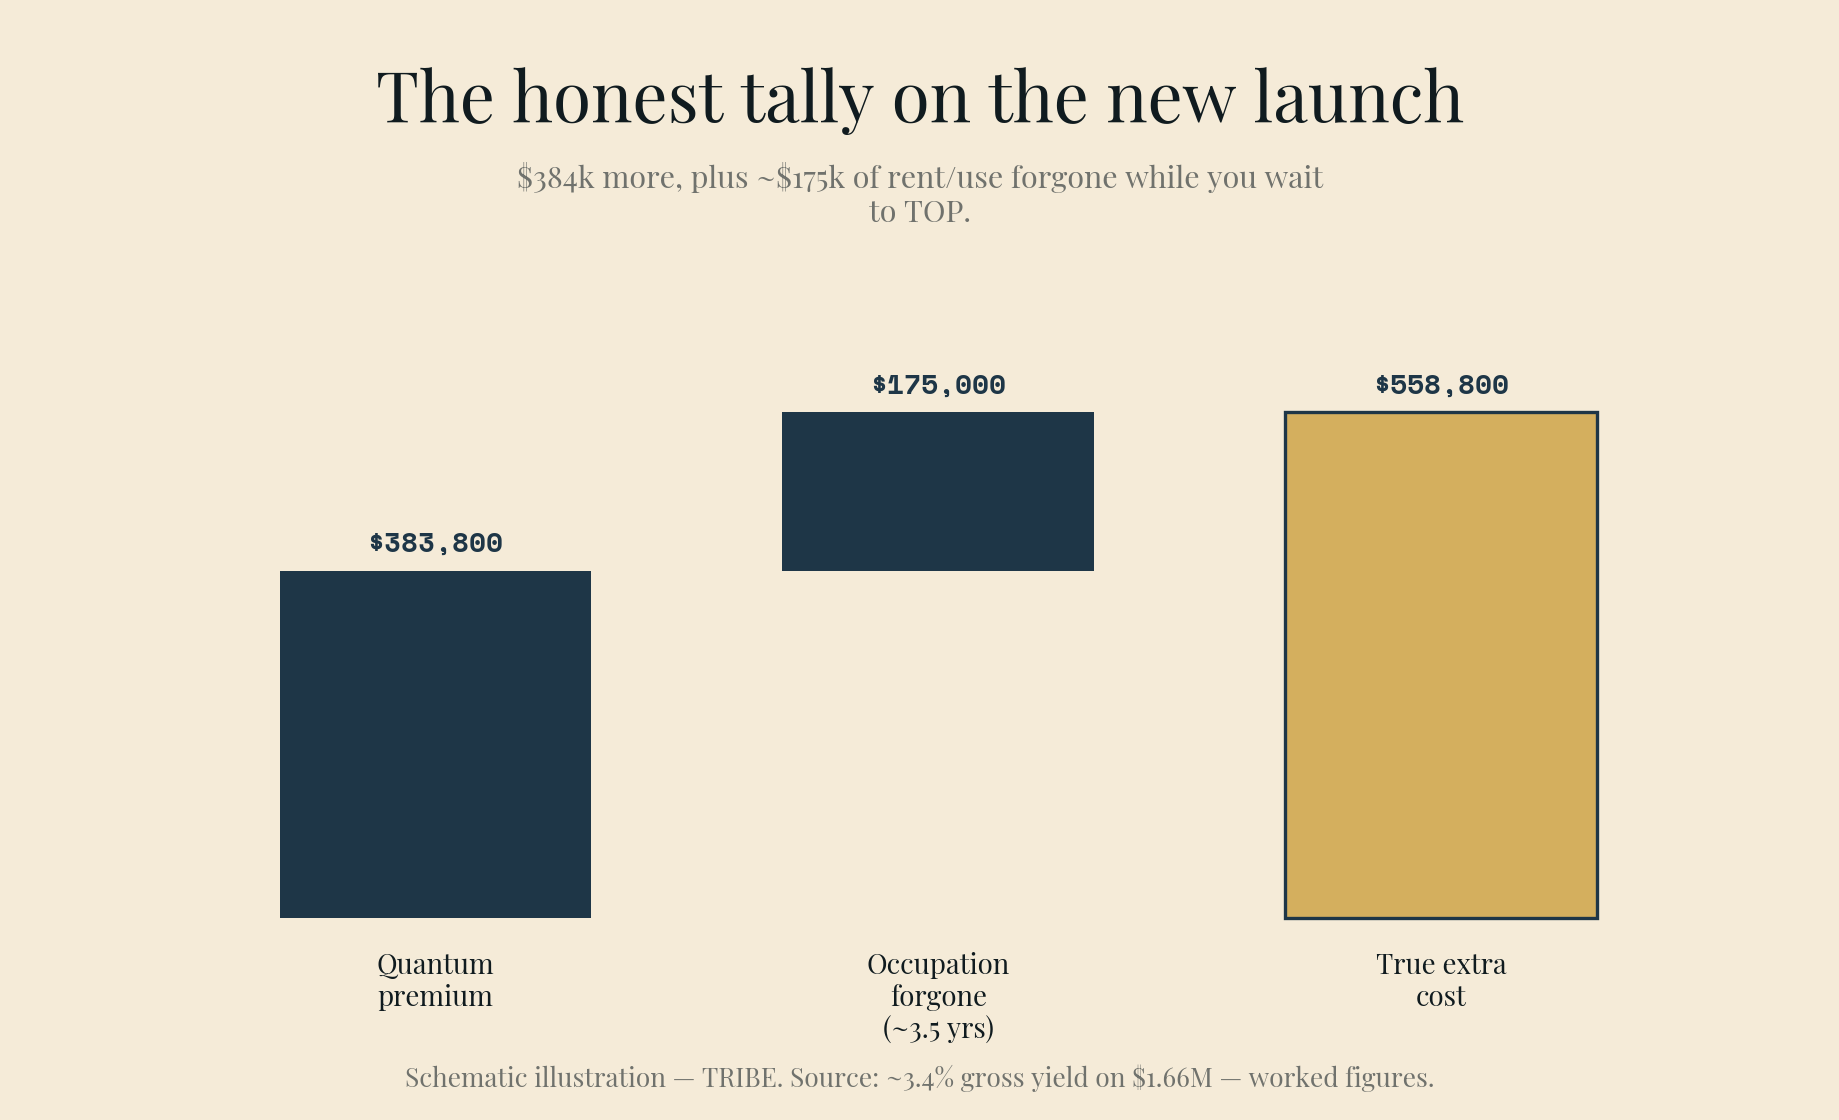
So the honest tally isn't just "S$384,000 more." It's S$384,000 more plus three-plus years without use of the asset, set against the new launch's lower early-interest carry, fresher lease, and zero renovation. Those don't net to zero — they net to a profile. New launch is a deferred, capital-preservation play that suits a buyer with time, a place to stay during construction, and a long hold. Resale is an immediate-utility play that suits a buyer who needs space now, wants a lower quantum and entry cost, and can absorb a renovation and an older lease.
Which way the 2026 market leans
Two data points frame the decision this year. First, resale isn't a discount bin: the median capital gain on a resale condo was about S$380,000 in early 2026, so the secondary market has been rewarding owners, not punishing them. Second, the new-launch premium is historically wide, which means more of your purchase price is the developer's margin and the brand-new tag — value that only crystallises if the project appreciates from an already-elevated base.
For an own-stay upgrader who needs the space and is sensitive to entry cost, the resale column does more work: you get the home now, at a lower quantum, with a smaller cheque upfront. For a buyer with a holding horizon beyond the lock-in, a comfortable interim living arrangement, and a preference for a full lease and staged outlay, the new launch's premium is buying something specific — and the progressive-payment structure softens the financing blow in the years before completion. Run the numbers on your flat, not the averages: the psf gap, the stamp duty, and the cost of waiting are all computable, and they decide this more cleanly than any "new versus old" instinct.
Sources: PropertyNet.SG, New Launch vs Resale Cost & Value Comparison 2026; PropertyGuru, 2026 OCR/RCR/CCR new-launch pricing; TRIBE, mid-2026 mortgage rates. Worked figures computed by TRIBE; illustrative, with assumptions stated above.
Silas Tan is a District Director at Huttons Asia and co-founder of TRIBE. This article is for informational purposes and does not constitute financial or investment advice. CEA Registration R000303I.
Check how your condo scores
2,350 condos independently scored across 7 weighted factors. No registration required.
Score my resale →Prefer a personal read on your situation? Arrange a consultation →Keep reading
3 November 2026Private Property Market
Less Than Half of an Entry Premium Comes Back. It Costs 0.69 Points a Year.
2 November 2026Private Property Market
Waiting Out a Launch Changes the Unit More Than It Changes the Price
1 November 2026Private Property Market
A Launch Sold Before Completion Earns Half a Point a Year More
Next step
TRIBE Research
Written with AI assistance from TRIBE's own data and the public sources listed, then checked against them. General information, not financial advice. How we write
How TRIBE scores and checks its analysis
Spotted an error, or a figure that has moved since publication? Tell us and we will correct it.
General information only, not financial, investment, legal or tax advice. It does not consider your own circumstances; check your own numbers before you commit.