Insights
The 3 Condos We Won't Recommend in Marine Parade / East Coast
The bottom of the Marine Parade / East Coast table isn't in a forgotten corner — it's the Meyer Road enclave, freehold and steps from a new TEL station. The sub-scores agree: cohort-lagging appreciation, yields of about 2% or less, no primary school within 1km.
By TRIBE Research · 12 June 2026 · Updated 16 October 2026 · 9 min read
District 15 is the largest district in our data — 434 scored resale projects, more than any other postal district in Singapore. The bottom of its Marine Parade / East Coast / Katong table is not where you might guess. It is not a remote walk-up far from transit. It is the Meyer Road enclave: freehold, sea-adjacent, and — since the Thomson-East Coast Line opened through here in 2024 — minutes on foot from an MRT station.
Three projects there carry a D grade, and the sub-scores behind each one tell the same story. Freehold tenure and doorstep MRT access are worth real points on the scorecard. They are not enough to outweigh appreciation that trails the same-era cohort, rental yields of about 2% or less, and no primary school within a kilometre.
How we ranked this
The Resale Project Scorecard (RPS) grades 2,350 resale condos on seven weighted factors: secondary market strength (25%), schools (20%), project size (16%), MRT proximity (13%), tenure (10%), rental yield (10%) and future transformation (6%). The secondary market score is cohort-relative — each condo is measured only against projects that reached TOP in the same two-year window, so an old project isn't penalised for being old, only for trailing its own vintage.
Three filters before ranking, stated plainly:
- Location. Districts aren't towns. D15 stretches from Tanjong Rhu and Mountbatten in the west to the Geylang fringe in the north. We kept only projects actually in the Marine Parade / East Coast / Katong area — which excludes, for instance, Park Court (RPS 4.91, at Lorong 101 Changi on the Eunos side).
- Still standing. Two of the area's former low scorers no longer exist as resale options: Meyer Park (RPS 3.29 when last scored) was sold en bloc for $392.18 million to a UOL–Singapore Land joint venture in February 2023 and is being redeveloped as Meyer Blue, and Lodge 77 (RPS 3.17 when last scored) has likewise gone to collective sale.
- Fully measured data only. Where the scorecard itself flags a placeholder — incomplete geocoding or a district-proxy yield — we set the project aside rather than rank it. That excludes Amber Glades (RPS 3.40, nominally the lowest in D15, but its schools and future transformation scores are flagged defaults; its measured factors are still weak — appreciation in the bottom 13% of its 1990-era cohort, 1.29% yield), along with Suites Twenty Two, Tian Court, Pomex Court and Klassic Court.
What remains is the three lowest fully-measured projects in the area. All three sit within walking distance of each other, between Katong Park and Tanjong Katong stations.
1. The Sovereign — RPS 3.92, Grade D
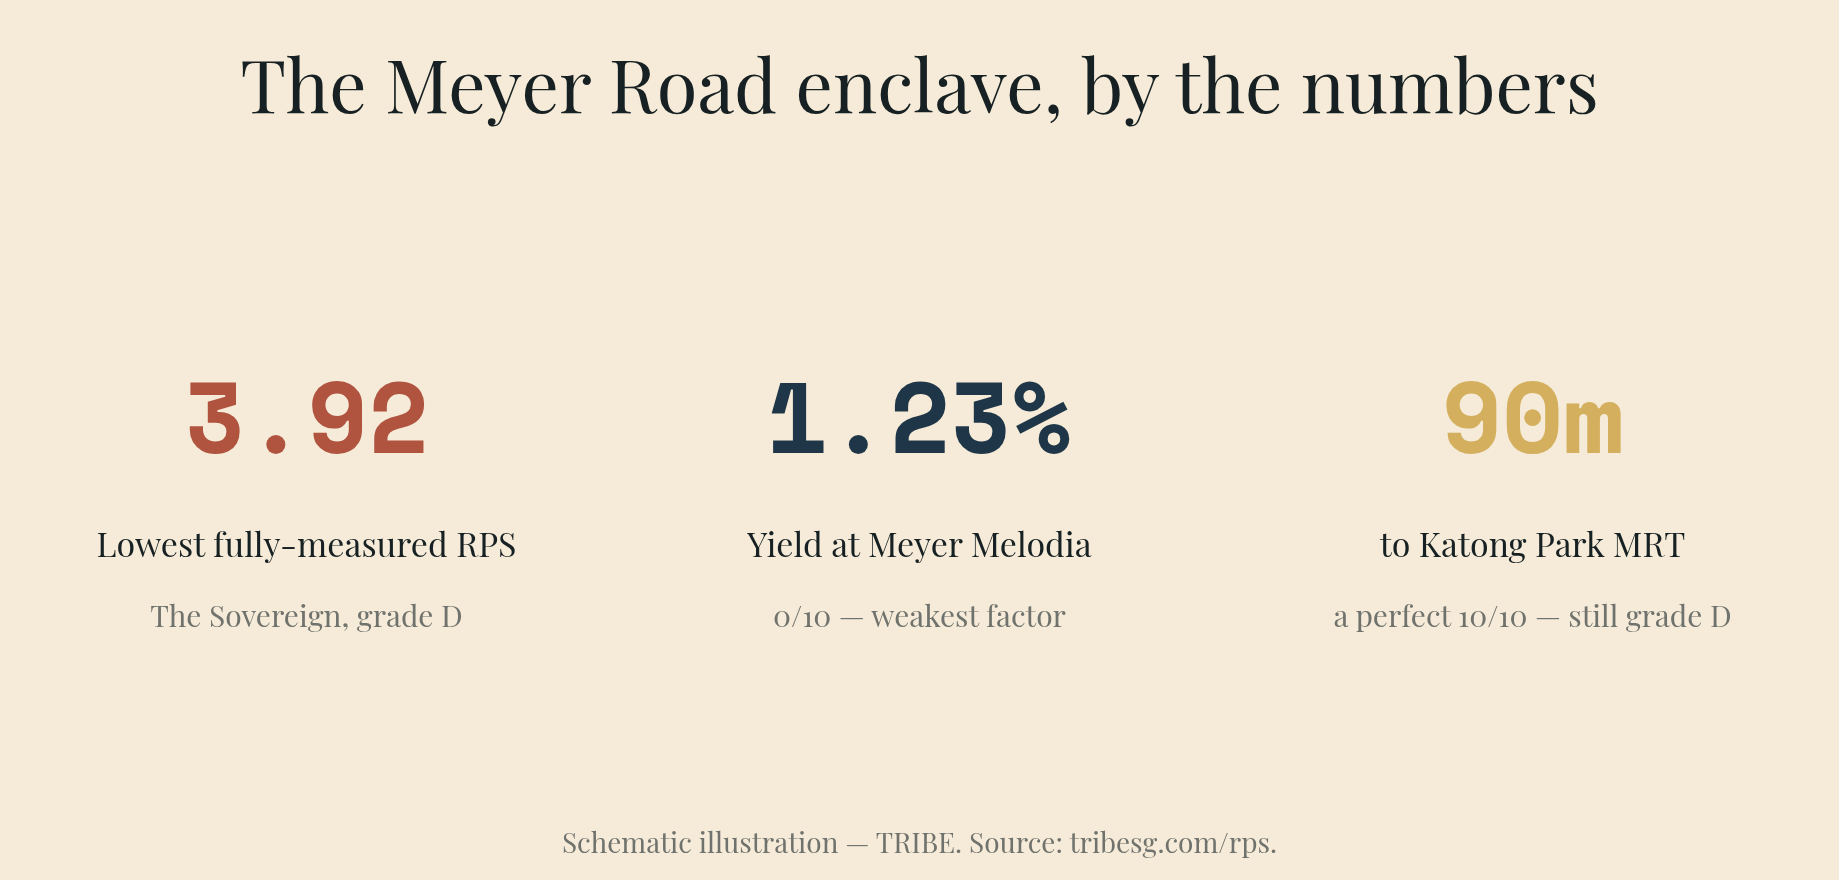
The biggest and best-known of the three: 87 freehold units on Meyer Road, completed in 1993, with the large-format floor plates the enclave is known for. It is also the lowest fully-measured score in the area.
- Secondary market: 4/10. "Avg Ann. of +3.12% — below-median performance vs same-vintage peers (39th percentile of 1993-era cohort)." Positive appreciation, but persistently behind its own generation.
- Rental yield: 0/10. 1.94% — "weak income return."
- Schools: 2/10. "No primary schools within 1km — school access is limited, particularly for parents prioritising Primary 1 registration."
- Project size: 3/10. 87 units — the largest of the three here, and still, in the scorecard's words, a "very small project; niche product with thin resale market."
- Future transformation: 0/10. No URA Master Plan zone or upcoming MRT station within 3.5km.
- MRT: 8/10. 490 m from Tanjong Katong station (TE25) — "short walk to MRT," the one factor where it concedes ground to the other two.
Its strongest factor is tenure, 10/10 for freehold. On the published weights, tenure and MRT together contribute about 2 points. Nothing else on the card scores above 4.
2. Meyer Melodia — RPS 3.93, Grade D
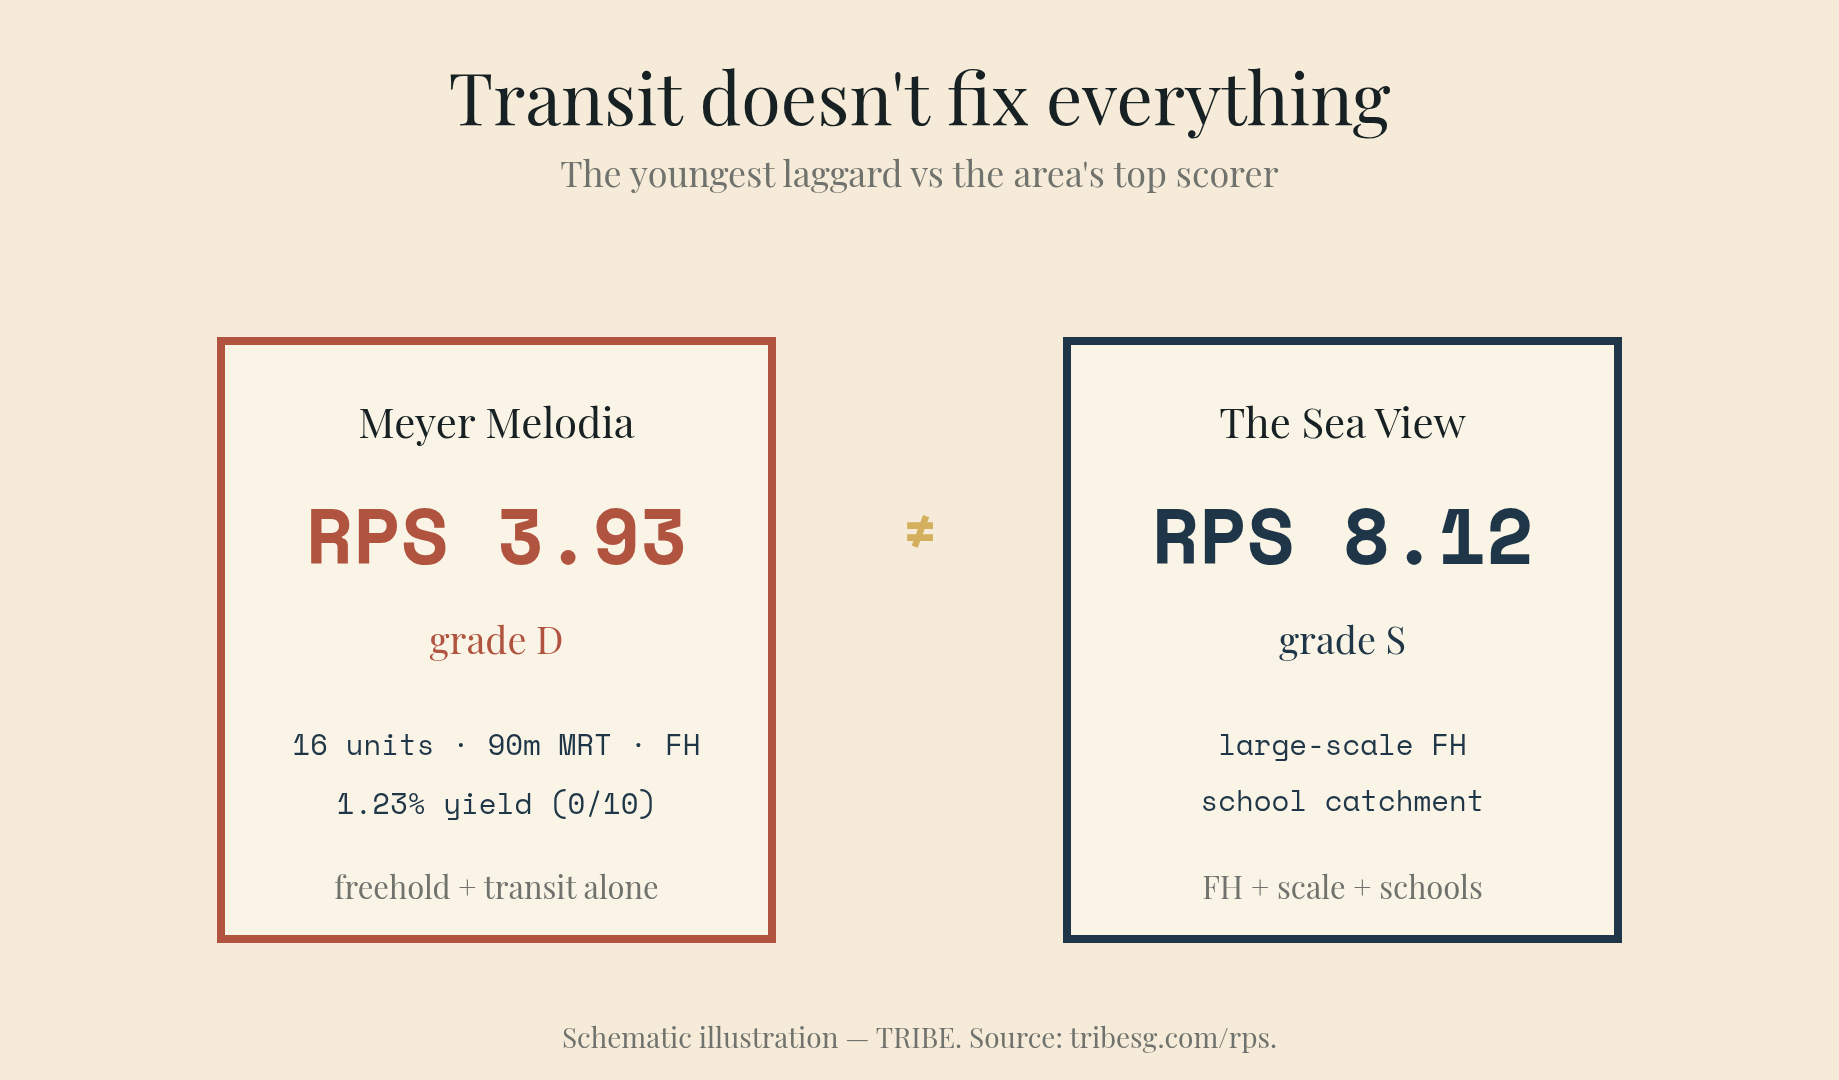
The youngest project in this article: a 16-unit freehold boutique at 2B Meyer Place, completed in 2017, 90 metres from Katong Park MRT. It sits a hundredth of a point above The Sovereign.
- Secondary market: 3/10. "Avg Ann. of +0.00% — below-median performance vs same-vintage peers (26th percentile of 2017-era cohort)." Its contemporaries — the 2016–2018 TOP generation — have moved ahead; it hasn't kept pace.
- Rental yield: 0/10. 1.23% — the lowest yield of the three, against capital values priced for freehold sea-fringe land.
- Schools: 2/10. No primary school within 1km.
- Project size: 3/10. 16 units. Thirteen of them are two-bedders under 730 sq ft — a single motivated seller can reset the project's comparable price for everyone.
A 2017-completion project with walk-in MRT access is the strongest possible test of the "transit fixes everything" thesis. The card says it doesn't: MRT 10/10 and tenure 10/10 — 2.3 points on the published weights — and the total still lands at 3.93.
3. Margate Point — RPS 4.15, Grade D
The smallest of the three: a 15-unit freehold block completed in 1998, 320 metres from Katong Park MRT (TE24) — "direct, walk-in MRT access."
- Secondary market: 4/10. "Avg Ann. of +2.90% — below-median performance vs same-vintage peers (39th percentile of 1998-era cohort)."
- Rental yield: 1/10. 2.18% — "weak income return."
- Schools: 2/10. No primary school within 1km.
- Project size: 3/10. 15 units — a "very small project; niche product with thin resale market."
- Future transformation: 0/10. No URA Master Plan zone or upcoming MRT station within 3.5km.
The pattern is the same as its neighbours: tenure 10/10 and MRT 9/10 carry the card, and everything that measures the resale market, the rent and the schools sits at 4 or below.
The scores, side by side
| RPS | Grade | Secondary | Yield | Schools | Size | MRT | Tenure | |
|---|---|---|---|---|---|---|---|---|
| The Sovereign | 3.92 | D | 4/10 | 0/10 (1.94%) | 2/10 | 3/10 (87 units) | 8/10 (490 m) | 10/10 (FH) |
| Meyer Melodia | 3.93 | D | 3/10 | 0/10 (1.23%) | 2/10 | 3/10 (16 units) | 10/10 (90 m) | 10/10 (FH) |
| Margate Point | 4.15 | D | 4/10 | 1/10 (2.18%) | 2/10 | 3/10 (15 units) | 9/10 (320 m) | 10/10 (FH) |
What separates these three from the rest of the area is not project size — the D15 average size score is just 3.6/10, because boutique stock dominates the whole district. And it is not future transformation, where the district averages a low 1.4/10 now that the TEL has opened and the catalyst is delivered. The separation is on the three factors that carry 55% of the weight: secondary market (these three score 3–4 against a district mean of 6.3), schools (2 against 6.7) and yield (0–1 against 3.9).
A note on The Meyer Place, which led this list when it was first published: its score has since risen to 4.43 (grade D). Its card now reads its capital record as "from only 1 resale sale in the last 10 years, too thin a sample to read capital appreciation reliably," so the scorecard discounts it toward the cohort average rather than marking it down. With 1.77% yield and no primary school within 1km it is still weak, but it is no longer one of the area's three lowest.
The en bloc wrinkle
There is one thing the RPS deliberately does not score: redevelopment optionality. Meyer Park — 60 freehold units, two doors down, RPS 3.29 before it left the data — sold collectively for $392.18 million in 2023, on its third attempt. Owners of ageing freehold boutiques on Meyer Road are, in part, holding a land position, and The Sovereign in particular is routinely named as a future collective-sale candidate.
That is a real but very different bet: multi-year timelines, 80% consensus requirements, and two failed attempts for every success on this street. The RPS measures what the resale market pays a unit-by-unit seller today. On that measure, all three have lagged for decades.
What this doesn't mean
These are not bad homes. The Meyer enclave is quiet, genuinely near the sea, freehold, and now better connected than it has ever been. The Sovereign's oversized layouts are the kind of stock that is no longer built. If you are buying space and address to live in, the scorecard is not measuring your use case.
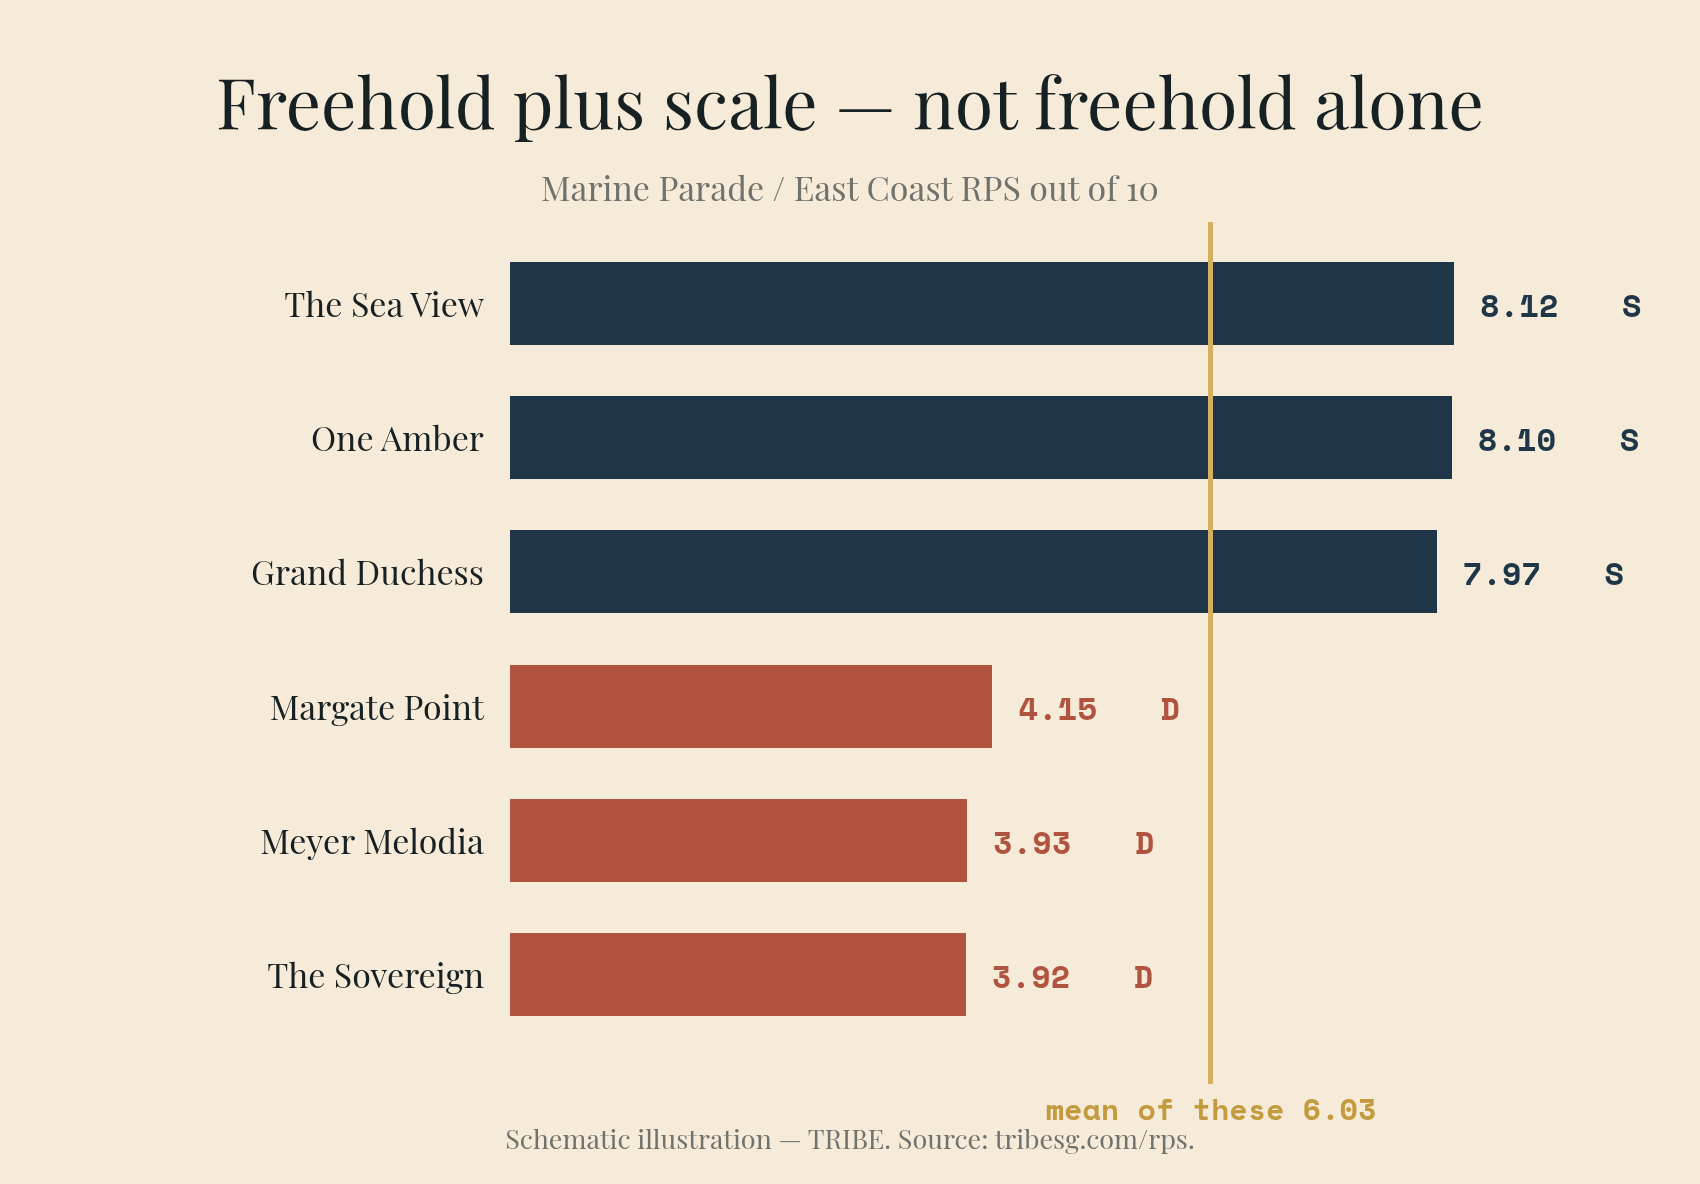
What the data does say: as resale investments, judged against their own same-era peers, all three sit in the bottom 3% of D15's 434 scored projects, with appreciation between the 26th and 39th percentile of their cohorts and yields of 1.23–2.18%. For contrast, the top of the same area — The Sea View (RPS 8.12), One Amber (8.10) and Grand Duchess @ St Patrick's (7.97), all S grade — shows what the market does reward here: freehold plus scale, school catchments and yields, not freehold alone.
Check How Your Condo Scores
Every project in this article is among the 2,350 independently scored across Singapore — each graded on seven weighted factors: secondary market performance, schools, size, MRT proximity, tenure, rental yield, and future transformation.
Score your resale condo on RPS →
No registration required. No agent call to follow. Just the data.
Scores and grades as at 16 October 2026.
Silas Tan is a District Director at Huttons Asia and co-founder of TRIBE. He built the Resale Project Scorecard (RPS) using 236,000+ URA REALIS transactions. This article is for informational purposes and does not constitute financial or investment advice. CEA Registration R000303I.
Condos in this article

Check how your condo scores
2,350 condos independently scored across 7 weighted factors. No registration required.
Score my resale →Prefer a personal read on your situation? Arrange a consultation →Keep reading
25 September 2026Resale Projects Reviews
Top 5 Condos in Changi and Loyang: One Factor Explains the Whole District
24 September 2026Resale Projects Reviews
Top 5 Condos in Holland, Tanglin and Bukit Timah — the Lowest-Scoring Large District in Singapore
23 September 2026Resale Projects Reviews
Top 5 Condos in Little India and Farrer Park — the Only Large District With No Failing Grade
Next step
TRIBE Research
Written with AI assistance from TRIBE's own data and the public sources listed, then checked against them. General information, not financial advice. How we write
How TRIBE scores and checks its analysis
Spotted an error, or a figure that has moved since publication? Tell us and we will correct it.
General information only, not financial, investment, legal or tax advice. It does not consider your own circumstances; check your own numbers before you commit.